The Miss
Let me start with the part I got wrong. On September 6 I put August headline CPI at +0.2%, inside a +0.1% to +0.3% range. It printed +0.4%. Friday's rebound in stocks does not soften that.
The call itself is still standing. I expect the Fed to hold on September 16, and I expect it with less confidence than I had on Wednesday night. The market has gone the other way: after CPI, futures put a hike near 90%, up from about 70% on Thursday (Reuters). Yesterday's note set two withdrawal conditions, core CPI of +0.4% or higher, or a hike on the 16th. Core came in at +0.3%. The line was not crossed. That keeps the call open. It does not make it right.
Estimates Against First Releases
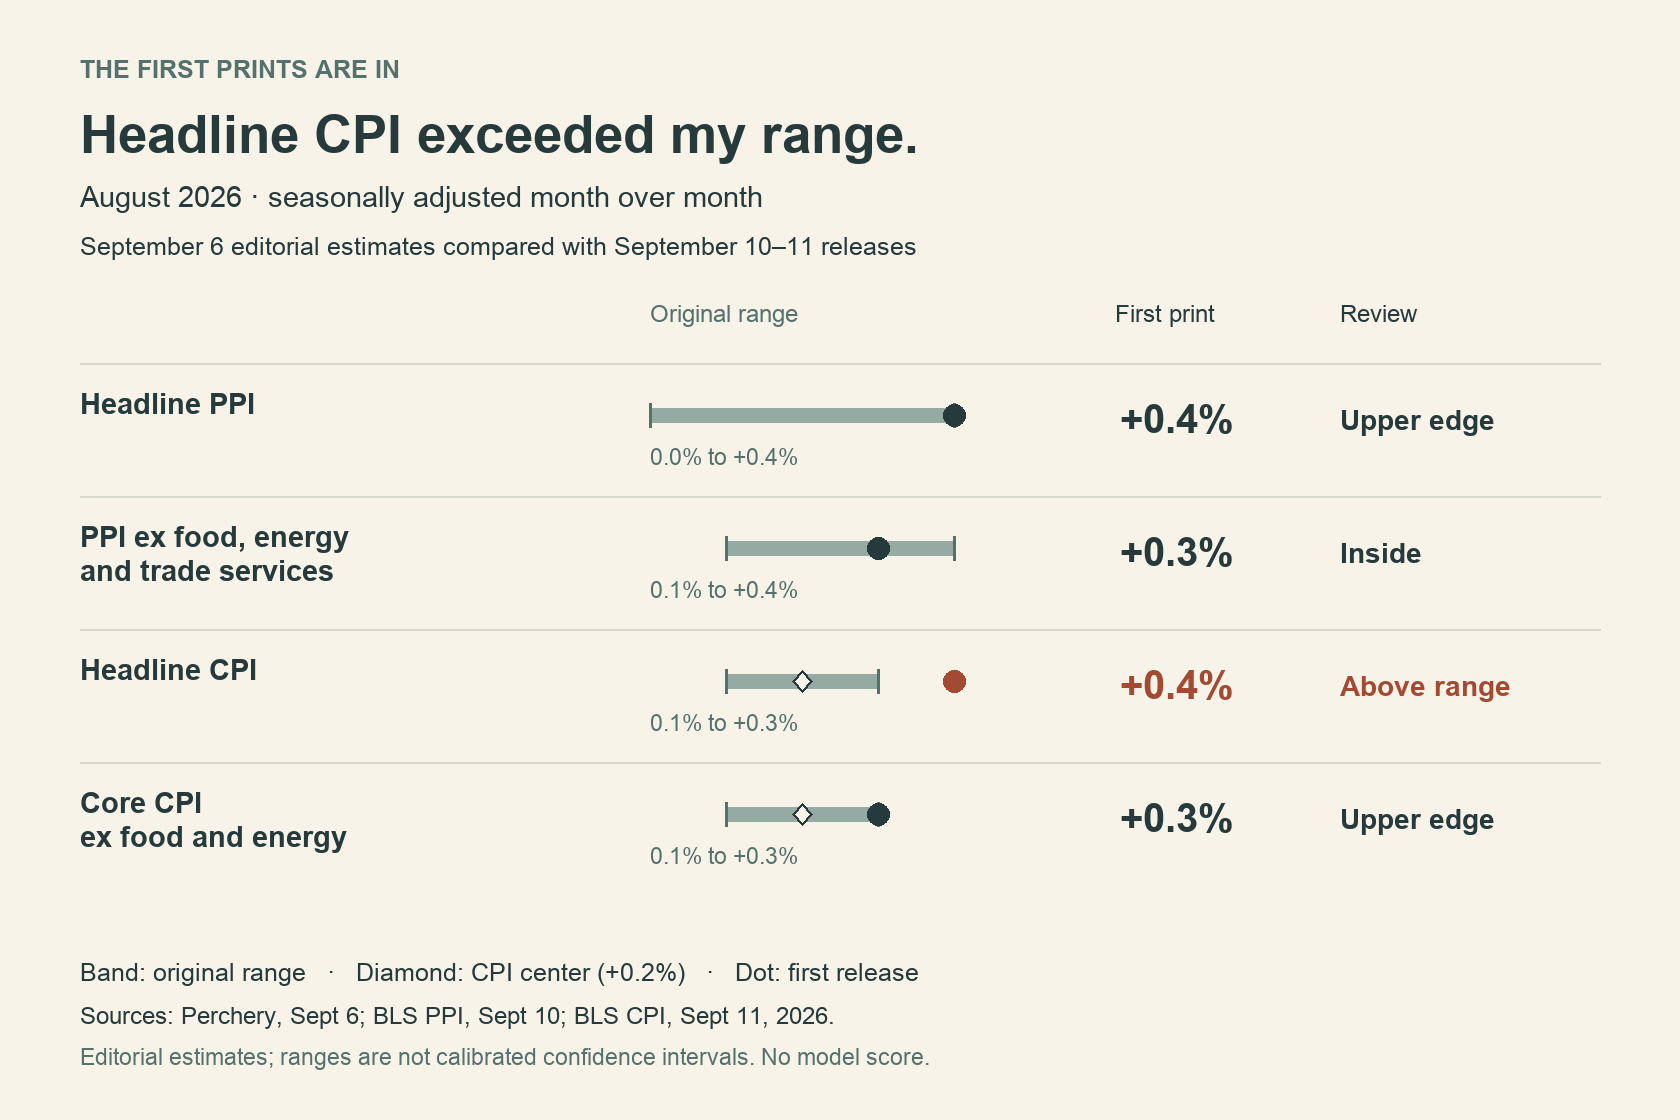
Here is the review I promised in Sunday's letter: all four estimates against the first releases. Everything below is August 2026, seasonally adjusted, month over month.
| Measure | September 6 center | Original range | First print | Review |
|---|---|---|---|---|
| Headline PPI | -- | 0.0% to +0.4% | +0.4% | Upper edge |
| PPI excluding food, energy and trade services | -- | +0.1% to +0.4% | +0.3% | Inside |
| Headline CPI | +0.2% | +0.1% to +0.3% | +0.4% | Above range |
| Core CPI, excluding food and energy | +0.2% | +0.1% to +0.3% | +0.3% | Upper edge |
Sources: BLS PPI, September 10, BLS CPI, September 11.
Both CPI centers were low. Core sat at the top of its range; headline went straight through it. These were editorial ranges, not calibrated intervals, and four observations are not a track record. They are still mine, so they get shown.
Evidence worth keeping in view
The main observations remain separate so one strong item cannot silently stand in for the whole case.
Headline PPI
Observed--
0.0% to +0.4% · +0.4% · Upper edge
PPI excluding food, energy and trade services
Mechanism--
+0.1% to +0.4% · +0.3% · Inside
Headline CPI
Inference+0.2%
+0.1% to +0.3% · +0.4% · Above range
Core CPI, excluding food and energy
Inference+0.2%
+0.1% to +0.3% · +0.3% · Upper edge
What Gasoline Explains and What It Does Not
Gasoline explains part of the miss. It rose 3.9% and carried more than a third of the headline increase. But shelter went from 0.1% in July to 0.3%, and core from 0.2% to 0.3%. That part is not gasoline, and I am not going to file it there. (BLS CPI).
Producer prices told the same story a day earlier. Energy supplied more than three-quarters of the rise in goods prices; that denominator matters. Strip out food, energy and trade services and PPI still rose 0.3%, after 0.4% in July. A big energy shock, with underlying pressure that has not gone away. (BLS PPI).
One housekeeping point. Sunday's letter described July headline PPI as flat, which is what the release said at the time. Thursday revised July to +0.1%. I am leaving the original estimate as written, with the information it was built on.
Friday's Disagreement Between Stocks and the Two-Year
Then there is Friday itself, where the two markets I watch most did not agree. The S&P 500 closed at 7,656.98, up 0.9%, still down 0.8% on the week (AP closing figures). AP's late-session report had the two-year Treasury yield at 4.64%, against 4.56% late Thursday. Stocks recovered; the yield that tracks the Fed's next move went up. Those are late-session figures rather than an official close, but the direction is the point (AP market report).
That is the uncomfortable part for me. A policy-sensitive yield rising into a rally fits a tougher expected Fed path. One day cannot isolate a cause. It can still point.
Why the Hold Call Stays
So why keep the call? Because the question in front of the Fed has not changed: is this an energy shock, or is it enough persistent inflation to justify raising rates again, now, with yields already doing part of the work? I still read it as the first, with the second getting harder to dismiss. My base case is a hawkish hold: unchanged rates, inflation risk front and center in the statement. Core at 0.3% makes that a closer judgment than I wanted. Staying under my own withdrawal line proves nothing. It is the absence of a trigger.
The TACO thesis from yesterday is in the same place. A stock rebound is not a walk-back. That needs an actual policy move before I can call it a walk-back.
What the September 16 Meeting Would Settle
The September 9-16 window is still running. Friday is one observation inside it; the 16th and the 17-18 follow-through are still ahead. The dates tell me when to look. They do not get credit for the direction.
At the September 15-16 meeting, a hike ends my no-hike call, plainly. A cut would also miss the specific outcome I expect. And even an unchanged rate leaves the question markets actually care about: whether yields let this rebound keep going.
I will write that review with the original call still beside it.
Source and Publication Record
This Free website mirror preserves the Perchery article dated 2026-09-11. Original content ID: perchery-2026-09-11-cpi-close-fed-test. Section headings label the original movement; the first-person interpretation remains Perchery's. This import does not convert the source into a Quant-native empirical audit.
Substack: https://perchery.substack.com/p/i-missed-headline-cpi-i-still-expect
X: https://x.com/readperchery/status/2098566037205635124
Bluesky: https://bsky.app/profile/perchery.bsky.social/post/3mvbshg2df22r
Information cutoff: September 11, 2026, after the US equity close; Treasury observations are AP late-session figures. The first-release review remains editorial and unscored. The September 16 hold-call review and September 17-18 follow-through remain open in this dated record. Inline link markup is adapted to plain text; original source URLs follow in order of appearance.
https://in.marketscreener.com/news/us-consumer-inflation-picks-up-in-august-ce785bdfdc8bf620
https://substack.com/@perchery/note/c-334334603
https://perchery.substack.com/p/the-dollar-stays-central-capital
https://www.bls.gov/news.release/archives/ppi_09102026.htm
https://www.bls.gov/news.release/cpi.nr0.htm
https://apnews.com/article/67a463295d9ea178d7802ca4338a6eb5
https://apnews.com/article/financial-markets-stocks-oil-iran-war-bonds-rates-8c3272812f5e9b9238c6a3301921c17a
https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm
Editorial research and personal judgment, not personalized investment advice or an instruction to transact.